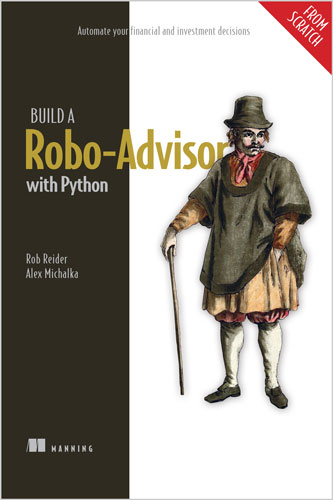
با ساخت یک ابزار مشاور مالی خودکار، قابل اعتماد و کارآمد، کنترل مدیریت ثروت خود را به دست بگیرید.
این کتاب به شما نشان میدهد که چگونه میتوانید یک مشاور مالی مبتنی بر پایتون بسازید. شما ابزاری انعطافپذیر و قدرتمند توسعه خواهید داد که قادر است یک استراتژی سرمایهگذاری واقعی را مدیریت کند، با استفاده از کتابخانههای رایگان و محبوب پایتون.
یاد خواهید گرفت که چگونه:
- اندازهگیری بازدهی و برآورد منافع روبو-مشاوران: سودآوری سرمایهگذاریهای خود را بسنجید و مزایای استفاده از مشاوران مالی خودکار را ارزیابی کنید.
- استفاده از شبیهسازیهای مونت کارلو: ابزارهای برنامهریزی مالی بسازید و آنها را آزمایش کنید.
- ساخت پرتفویهای متنوع و کارآمد: با به کارگیری بهینهسازی و سایر روشهای پیشرفته، پرتفویهای متنوع و سودده ایجاد کنید.
- پیادهسازی و ارزیابی روشهای تعدیل مجدد (Rebalancing): برای پیگیری پرتفوی هدف در طول زمان، استراتژیهای تعدیل مجدد را به کار ببرید.
- کاهش مالیاتها: از طریق برداشت ضرر مالیاتی (Tax-loss harvesting) و توالی بهینه برداشتها، میزان پرداختیهای مالیاتی خود را کاهش دهید.
- به کارگیری یادگیری تقویتی: مسیر سرمایهگذاری بهینه تا زمان بازنشستگی و پس از آن را کشف کنید.
دربارهی نویسندگان
راب رایدر، مدیر پرتفوی با بیش از ۱۵ سال تجربه، دکترای مالی از وارتون، و استاد مدعو در NYU که در زمینه مدلسازی تخصیص دارایی و ابزارهای مالی مبتنی بر پایتون تخصص دارد.
الکس میچالکا، فعال از ۲۰۰۶ در حوزه مالی و فناوری، با تجربه در مدلسازی قیمتگذاری مشتقات و ساختار پرتفوی، و رهبر گروه تحقیقات سرمایهگذاری در Wealthfront با مدرک ریاضیات کاربردی و دکترای تحقیقات عملیاتی.
Take control of your wealth management by building your own reliable, effective, and automated financial advisor tool.
In Build a Robo-Advisor with Python (From Scratch) you’ll learn how to:
- Measure returns and estimate the benefits of robo-advisors
- Use Monte Carlo simulations to build and test financial planning tools
- Construct diversified, efficient portfolios using optimization and other advanced methods
- Implement and evaluate rebalancing methods to track a target portfolio over time
- Decrease taxes through tax-loss harvesting and optimized withdrawal sequencing
- Use reinforcement learning to find the optimal investment path up to, and after, retirement
Every day automated digital advisors, also called robo-advisors, make financial decisions worth millions of dollars. Build a Robo-Advisor with Python (From Scratch): Automate your financial and investment decisions teaches you how to construct a Python-based financial advisor of your very own! You’ll develop a flexible tool that’s capable of managing a real investing strategy—all with popular free Python libraries.
About the technology
Automated “robo-advisors” are commonplace in financial services, thanks to their ability to give high-quality investment advice at a fraction of the cost of human advisors. Your own robo advisor will be a real asset for your financial planning, whether you’re saving for retirement, creating a diversified portfolio, or trying to ensure your tax efficiency.
About the book
In Build a Robo-Advisor with Python (From Scratch), you’ll design and develop a working financial advisor that can manage a real investing strategy. You’ll add new features to your advisor chapter-by-chapter, including determining the optimal weight of cryptocurrency in your portfolio, rebalancing to keep your investments on target while minimizing taxes, and using reinforcement learning to find a “glide path” that can maximize how long your money will last in retirement. Best of all, the skills you learn in reinforcement learning, convex optimization, and Monte Carlo methods can be applied to numerous lucrative fields beyond the domain of finance.
About the reader
The book is accessible to anyone with a basic knowledge of Python and finance—no special skills required.
Table of Contents
Part 1: Basic tools and building blocks
1. The rise of robo-advisors
2. An introduction to portfolio construction
3. Estimating expected returns and covariances
4. ETFs: The building blocks of robo-portfolios
Part 2: Financial planning tools
5. Monte Carlo simulations
6. Financial planning using reinforcement learning
7. Measuring and evaluating returns
8. Asset location
9. Tax-efficient withdrawal strategies
Part 3: Portfolio construction
10. Optimization and portfolio construction
11. Asset allocation by risk: Introduction to risk parity
12. The Black-Litterman model
Part 4: Portfolio management
13. Rebalancing: Tracking a target portfolio
14. Tax-loss harvesting: Improving after-tax returns
About the Author
Rob Reider has been a quantitative hedge fund portfolio manager for over 15 years. He holds a PhD in Finance from The Wharton School and is an Adjunct Professor at NYU, where he teaches a graduate course in the Math-Finance department called “Time Series Analysis and Statistical Arbitrage.” He has built asset allocation models, financial planning tools, and optimal tax strategies for a robo-advisor. Rob has given numerous lectures that combine Python with finance, as well as developing an online course entitled “Time Series Analysis in Python.” As a hedge fund manager, Rob has been involved in all aspects of the investment process, from discovering new trading strategies to backtesting, executing, and managing the risk.
Alex Michalka has worked in finance and technology since 2006. He began his career developing weather derivative pricing models at Weatherbill, spent six years conducting research on quantitative equity portfolio construction at AQR Capital Management, and currently leads the investments research group at Wealthfront. He holds a BA in applied mathematics from UC Berkeley and a PhD in operations research from Columbia University.

نقد و بررسیها
هنوز بررسیای ثبت نشده است.