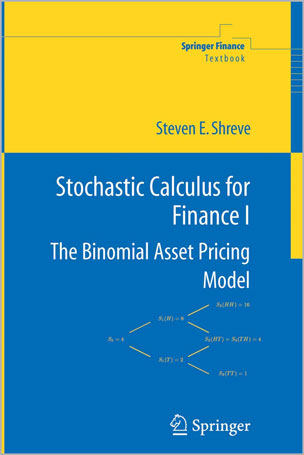
Stochastic Calculus for Finance evolved from the first ten years of the Carnegie Mellon Professional Master’s program in Computational Finance. The content of this book has been used successfully with students whose mathematics background consists of calculus and calculus-based probability. The text gives both precise statements of results, plausibility arguments, and even some proofs, but more importantly intuitive explanations developed and refine through classroom experience with this material are provided. The book includes a self-contained treatment of the probability theory needed for stochastic calculus, including Brownian motion and its properties. Advanced topics include foreign exchange models, forward measures, and jump-diffusion processes.
This book is being published in two volumes. The first volume presents the binomial asset-pricing model primarily as a vehicle for introducing in the simple setting the concepts needed for the continuous-time theory in the second volume.
Chapter summaries and detailed illustrations are included. Classroom tested exercises conclude every chapter. Some of these extend the theory and others are drawn from practical problems in quantitative finance.
Advanced undergraduates and Masters level students in mathematical finance and financial engineering will find this book useful.
Table of Contents
1 The Binomial No-Arbitrage Pricing Model
2 Probability Theory on Coin Toss Space
3 State Prices
4 American Derivative Securities
5 Random Walk
6 Interest-Rate-Dependent Assets
About the Author
Steven E. Shreve is Co-Founder of the Carnegie Mellon MS Program in Computational Finance and winner of the Carnegie Mellon Doherty Prize for sustained contributions to education.


نقد و بررسیها
هنوز بررسیای ثبت نشده است.