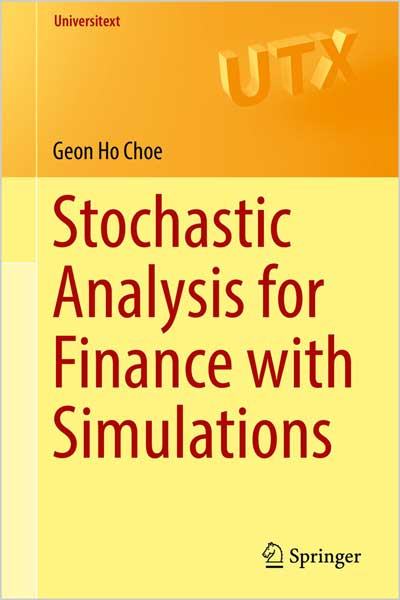
This book is an introduction to stochastic analysis and quantitative finance; it includes both theoretical and computational methods. Topics covered are stochastic calculus, option pricing, optimal portfolio investment, and interest rate models. Also included are simulations of stochastic phenomena, numerical solutions of the Black–Scholes–Merton equation, Monte Carlo methods, and time series. Basic measure theory is used as a tool to describe probabilistic phenomena.
The level of familiarity with computer programming is kept to a minimum. To make the book accessible to a wider audience, some background mathematical facts are included in the first part of the book and also in the appendices. This work attempts to bridge the gap between mathematics and finance by using diagrams, graphs and simulations in addition to rigorous theoretical exposition. Simulations are not only used as the computational method in quantitative finance, but they can also facilitate an intuitive and deeper understanding of theoretical concepts.
Stochastic Analysis for Finance with Simulations is designed for readers who want to have a deeper understanding of the delicate theory of quantitative finance by doing computer simulations in addition to theoretical study. It will particularly appeal to advanced undergraduate and graduate students in mathematics and business, but not excluding practitioners in finance industry.
Table of Contents
Part I Introduction to Financial Mathematics
1 Fundamental Concepts
2 Financial Derivatives
Part II Probability Theory
3 The Lebesgue Integral
4 Basic Probability Theory
5 Conditional Expectation
6 Stochastic Processes
Part Ill Brownian Motion
7 Brownian Motion
8 Girsanov’s Theorem
9 The Reflection Principle of Brownian Motion
Part IV lt6 Calculus
10 The lt6 Integral
11 The Ito Formula
12 Stochastic Differential Equations
13 The Feynman-Kac Theorem
Part V Option Pricing Methods
14 The Binomial Tree Method for Option Pricing
15 The Black-Scholes-Merton Differential Equation
16 The Martingale Method
Part VI Examples of Option Pricing
17 Pricing of Vanilla Options
18 Pricing of Exotic Options
19 American Options
Part VII Portfolio Management
20 The Capital Asset Pricing Model
21 Dynamic Programming
Part VIII Interest Rate Models
22 Bond Pricing
23 Interest Rate Models
24 Numeraires
Part IX Computational Methods
25 Numerical Estimation of Volatility
26 Time Series
27 Random Numbers
28 The Monte Carlo Method for Option Pricing
29 Numerical Solution of the Black-Scholes-Merton Equation
30 Numerical Solution of Stochastic Differential Equations
A Basic Analysis
B linear Algebra
C Ordinary Differential Equations
D Diffusion Equations
E Entropy
F Matlab Programming
Solutions for Selected Problems


نقد و بررسیها
هنوز بررسیای ثبت نشده است.