💹 درک جامعی از انواع ریسکهای مالی، مزایای تنوعبخشی سبد سرمایهگذاری و رابطهٔ بنیادین میان ریسک و بازده بهدست آورید.
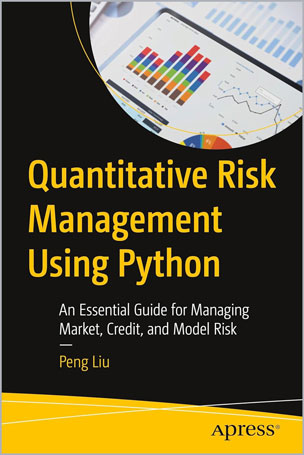
این کتاب سفری عمیق به دنیای مدیریت کمی ریسک با پایتون است، با تمرکز بر ریسک اعتباری و ریسک بازار، و نگاهی گسترشیافته به ریسک مدل.
📊 در آغاز، با انواع مختلف ریسکهای مالی، مزایای تنوع در سبد سرمایهگذاری و مبادلهٔ اصلی میان ریسک و بازده آشنا میشوید. سپس، کتاب بهصورت کاربردی به بررسی روشهای مدیریت ریسک اعتباری و بازار در فضای پویای مالی امروز میپردازد — همه با پیادهسازیهای واقعی در پایتون. در ادامه، با استراتژیهای پوشش ریسک (Hedging) برای مدیریت موقعیتهای سرمایهگذاری آشنا میشوید و یاد میگیرید چگونه شاخصهای ریسک تعدیلشده و ریسک نزولی را محاسبه و تحلیل کنید. در پایان، با ریسکهای مرتبط با توسعه و استفاده از مدلهای یادگیری ماشین در مالی آشنا خواهید شد.
📈 چه متخصص مالی باشید، چه پژوهشگر یا دانشجو، این کتاب شما را توانمند میسازد تا در فضای پیچیدهٔ مالی امروز تصمیمهای آگاهانه و مبتنی بر داده بگیرید.
📘 آنچه خواهید آموخت:
- بررسی و مدیریت ریسک نکول و طرف مقابل در وامگیرندگان و قراردادها
- شناسایی، اندازهگیری و کاهش ریسکهای ناشی از نوسانات قیمتهای بازار
- درک نحوهٔ استفاده از ابزارهای مشتقه (Derivatives) برای پوشش ریسک
- آشنایی با روشهای پوشش ایستا و پویا برای محافظت از موقعیتهای سرمایهگذاری، همراه با پیادهسازیهای عملی
- شناسایی و مدیریت ریسکهای مربوط به مدلهای یادگیری ماشین در مالی
🎯 مخاطبان:
متخصصان مالی، دانشگاهیان و دانشجویانی که بهدنبال درک عمیقتر از مدیریت کمی ریسک با پایتون هستند، بهویژه آنهایی که در حوزههای ریسک اعتباری، بازار و مدل فعالیت میکنند.
📑 فهرست فصلها:
۱. مقدمهای بر مدیریت کمی ریسک
۲. مبانی ریسک و بازده در مالی
۳. مدیریت ریسک اعتباری
۴. مدیریت ریسک بازار
۵. مدیریت ریسک با استفاده از مشتقات مالی
۶. پوشش ریسک ایستا و پویا
۷. مدیریت ریسک مدل در امور مالی
👨🏫 دربارهٔ نویسنده:
پِنگ لیو (Peng Liu) استادیار مالی کمی (عملی) در دانشگاه مدیریت سنگاپور و پژوهشگر وابسته در دانشگاه ملی سنگاپور است. او دارای دکترای آمار از همان دانشگاه بوده و بیش از ده سال تجربه در صنایع بانکداری، فناوری و گردشگری دارد. لیو نویسندهٔ دو کتاب دیگر از انتشارات Apress است:
📘 Bayesian Optimization (2023)
📘 Quantitative Trading Strategies Using Python (2023)
Gain an understanding of various financial risks, the benefits of portfolio diversification, and the fundamental trade-off between risk and return. This book takes an in-depth journey into the world of quantitative risk management using Python, focusing on credit and market risk, with an extension to model risk.
You’ll start by reviewing the different types of financial risk, the benefit of diversification in a portfolio, and the fundamental trade-off between risk and return. The book then offers an in-depth look at managing credit and market risk in today’s dynamic markets, all with practical Python implementations. Moving on, you’ll examine common hedging strategies used to manage investment positions, along with practical implementations on evaluating risk-adjusted, as well as downside risk measures. Finally, you’ll be introduced to common risks related to the development and use of machine learning models in finance.
Whether you’re a finance professional, academic, or student, Quantitative Risk Management Using Python will empower you to make informed decisions in today’s complex financial landscape.
What You Will Learn
- Explore techniques to assess and manage the risk of default by borrowers or counterparties.
- Identify, measure, and mitigate risks arising from fluctuations in market prices.
- Understand how derivatives can be employed for risk management purposes.
- Delve into both static and dynamic hedging techniques to protect investment positions, including practical applications for evaluating risk-adjusted and downside risk measures.
- Identify and address risks associated with the development and deployment of machine learning models in financial contexts.
Who This Book Is For
Finance professionals, academics, and students seeking to deepen their understanding of Quantitative Risk Management using Python, especially those interested in navigating the intricate domains of credit, market and model risk within the financial sector and beyond.
Table of Contents
1 Introduction to Quantitative Risk Management
2 Fundamentals of Risk and Return in Finance
3 Managing Credit Risk
4 Managing Market Risk
5 Risk Management Using Financial Derivatives
6 Static and Dynamic Hedging
7 Managing Model Risk in Finance
About the Author
Peng Liu is an Assistant Professor of Quantitative Finance (Practice) at Singapore Management University and an adjunct researcher at the National University of Singapore. He holds a Ph.D. in statistics from the National University of Singapore and has over 10 years of working experience across the banking, technology, and hospitality industries. Peng is the author of Bayesian Optimization (Apress, 2023) and Quantitative Trading Strategies Using Python (Apress, 2023)

نقد و بررسیها
هنوز بررسیای ثبت نشده است.