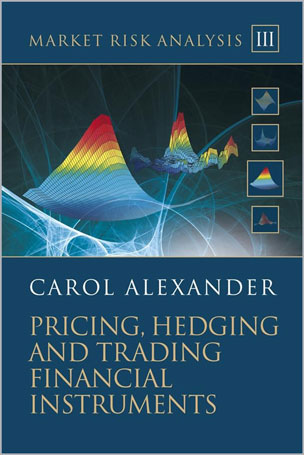
Written by leading market risk academic, Professor Carol Alexander, Pricing, Hedging and Trading Financial Instruments forms part three of the Market Risk Analysis four volume set. This book is an in-depth, practical and accessible guide to the models that are used for pricing and the strategies that are used for hedging financial instruments, and to the markets in which they trade. It provides a comprehensive, rigorous and accessible introduction to bonds, swaps, futures and forwards and options, including variance swaps, volatility indices and their futures and options, to stochastic volatility models and to modelling the implied and local volatility surfaces.
All together, the Market Risk Analysis four volume set illustrates virtually every concept or formula with a practical, numerical example or a longer, empirical case study. Across all four volumes there are approximately 300 numerical and empirical examples, 400 graphs and figures and 30 case studies many of which are contained in interactive Excel spreadsheets available from the the accompanying CD-ROM . Empirical examples and case studies specific to this volume include:
- Duration-Convexity approximation to bond portfolios, and portfolio immunization;
- Pricing floaters and vanilla, basis and variance swaps;
- Coupon stripping and yield curve fitting;
- Proxy hedging, and hedging international securities and energy futures portfolios;
- Pricing models for European exotics, including barriers, Asians, look-backs, choosers, capped, contingent, power, quanto, compo, exchange, ‘best-of’ and spread options;
- Libor model calibration;
- Dynamic models for implied volatility based on principal component analysis;
- Calibration of stochastic volatility models (Matlab code);
- Simulations from stochastic volatility and jump models;
- Duration, PV01 and volatility invariant cash flow mappings;
- Delta-gamma-theta-vega mappings for options portfolios;
- Volatility beta mapping to volatility indices.
Table of Contents
III.1 Bonds and Swaps
III.2 Futures and Forwards
III.3 Options
III.4 Volatility
III.5 Portfolio Mapping
About the Author
Carol Alexander is one of the world’s leading authorities on market risk analysis. She is Professor of Financial Risk Management at the ICMA Centre, University of Reading where she directs a vibrant research group focusing on quantitative financial risk management. In her role as Chair of the Academic Advisory Council of the Professional Risk Manager’s International Association (PRMIA) she has been a driving force for the setting of global standards in the financial risk management profession. Her untiring work on the Professional Risk Manager’s Handbook and on classroom and distance learning training courses now provides the means to achieve these standards. She has published around 100 academic journal articles, book chapters and books, and now ranks amongst the world’s best-known authors in financial risk management and quantitative finance.

نقد و بررسیها
هنوز بررسیای ثبت نشده است.