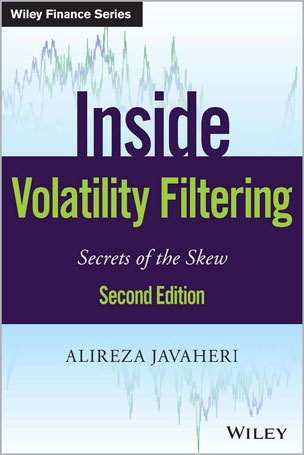
Inside Volatility Filtering presents a new approach to volatility estimation, using financial econometrics based on a more accurate estimation of the hidden state. Based on the idea of “filtering”, this book lays out a two-step framework involving a Chapman-Kolmogorov prior distribution followed by Bayesian posterior distribution to develop a robust estimation based on all available information. This new second edition includes guidance toward basing estimations on historic option prices instead of stocks, as well as Wiener Chaos Expansions and other spectral approaches. The author’s statistical trading strategy has been expanded with more in-depth discussion, and the companion website offers new topical insight, additional models, and extra charts that delve into the profitability of applied model calibration. You’ll find a more precise approach to the classical time series and financial econometrics evaluation, with expert advice on turning data into profit.
Financial markets do not always behave according to a normal bell curve. Skewness creates uncertainty and surprises, and tarnishes trading performance, but it’s not going away. This book shows traders how to work with skewness: how to predict it, estimate its impact, and determine whether the data is presenting a warning to stay away or an opportunity for profit.
- Base volatility estimations on more accurate data
- Integrate past observation with Bayesian probability
- Exploit posterior distribution of the hidden state for optimal estimation
- Boost trade profitability by utilizing “skewness” opportunities
Wall Street is constantly searching for volatility assessment methods that will make their models more accurate, but precise handling of skewness is the key to true accuracy. Inside Volatility Filtering shows you a better way to approach non-normal distributions for more accurate volatility estimation.
Table of Contents
1 The Volatility Problem
2 The Inference Problem
3 The Consistency Problem
4 The Quality Problem
About the Author
Alireza Javaheri is the head of Equities Quantitative Research Americas at JP Morgan and an adjunct professor of Mathematical Finance at the Courant Institute of New York University, as well as Baruch College. He has worked in the field of derivatives quantitative research since 1994 in a variety of investment banks, including Goldman Sachs and Citigroup.


نقد و بررسیها
هنوز بررسیای ثبت نشده است.