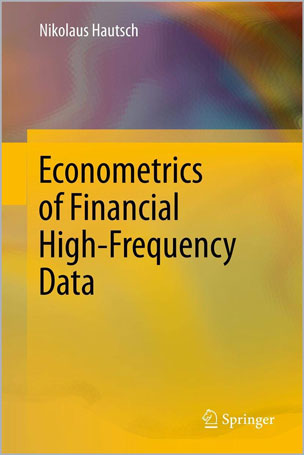
The availability of financial data recorded on high-frequency level has inspired a research area which over the last decade emerged to a major area in econometrics and statistics. The growing popularity of high-frequency econometrics is driven by technological progress in trading systems and an increasing importance of intraday trading, liquidity risk, optimal order placement as well as high-frequency volatility. This book provides a state-of-the art overview on the major approaches in high-frequency econometrics, including univariate and multivariate autoregressive conditional mean approaches for different types of high-frequency variables, intensity-based approaches for financial point processes and dynamic factor models. It discusses implementation details, provides insights into properties of high-frequency data as well as institutional settings and presents applications to volatility and liquidity estimation, order book modelling and market microstructure analysis.
Table of Contents
Chapter 1: Introduction
Chapter 2: Microstructure Foundations
Chapter 3: Empirical Properties of High-Frequency Data
Chapter 4: Financial Point Processes
Chapter 5: Univariate Muliplicative Error Models
Chapter 6: Generalized Multiplicative Error Models
Chapter 7: Vector Multiplicative Error Models
Chapter 8: Modelling High-Frequency Volatility
Chapter 9: Estimating Market Liquidity
Chapter 10: Semiparametric Dynamic Proportional Hazard Models
Chapter 11 : Univariate Dynamic Intensity Models
Chapter 12: Multivariate Dynamic Intensity Models
Chapter 13: Autoregressive Discrete Processes and Quote Dynamics
Appendix A: Important Distributions for Positive-Valued Data
About the Author
Nikolaus Hautsch, born 1972, is director of the Institute for Econometrics at the Department of Economics and Business Administration at the Humboldt-Universität zu Berlin since 2007. His research interests are financial econometrics, empirical finance and multivariate time series analysis. Particular focus is on the econometric modelling of financial high-frequency data, market microstructure analysis as well as volatility and liquidity estimation.


نقد و بررسیها
هنوز بررسیای ثبت نشده است.