انتشار گسترده هوش مصنوعی و یادگیری ماشین در حال تحول بسیاری از صنایع امروز است. زمانی که این تکنولوژیها با دسترسی برنامهریزی شده به دادههای تاریخی و زمان واقعی مالی ترکیب شوند، صنعت مالی نیز به طور بنیادی تغییر خواهد کرد. در این کتاب عملی، شما خواهید آموخت که چگونه از هوش مصنوعی و یادگیری ماشین برای کشف ناکارآمدیهای آماری در بازارهای مالی و بهرهبرداری از آنها از طریق معاملات الگوریتمی استفاده کنید.
نویسنده، ایو هیلپیچ، روشهای عملی استفاده از الگوریتمهای یادگیری ماشین و یادگیری عمیق در مالی را به متخصصان، دانشجویان و محققان در زمینههای مالی و علم داده نشان میدهد. با توجه به مثالهای متعدد Python که به طور مستقل توضیح داده شدهاند، شما قادر خواهید بود تمام نتایج و نمودارهای ارائه شده در کتاب را تکرار کنید.
این راهنما در پنج بخش به شما کمک میکند تا:
- مفاهیم و الگوریتمهای اصلی هوش مصنوعی را بیاموزید، از جمله پیشرفتهای اخیر در مسیر دستیابی به هوش مصنوعی عمومی (AGI) و ابرهوش (SI)
- درک کنید که چرا مالی دادهمحور، هوش مصنوعی و یادگیری ماشین تأثیرات ماندگاری بر تئوری و عمل مالی خواهند داشت
- از شبکههای عصبی و یادگیری تقویتی برای کشف ناکارآمدیهای آماری در بازارهای مالی استفاده کنید
- ناکارآمدیهای اقتصادی را از طریق آزمونهای بازگشتی و معاملات الگوریتمی—اجرای خودکار استراتژیهای معاملاتی—شناسایی و بهرهبرداری کنید
- درک کنید که هوش مصنوعی چگونه دینامیک رقابتی در صنعت مالی را تحت تأثیر قرار خواهد داد و ظهور احتمالی تکینگی مالی چه پیامدهایی خواهد داشت
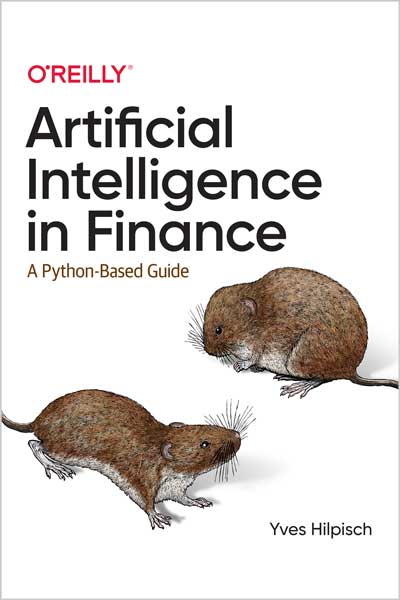
The widespread adoption of AI and machine learning is revolutionizing many industries today. Once these technologies are combined with the programmatic availability of historical and real-time financial data, the financial industry will also change fundamentally. With this practical book, you’ll learn how to use AI and machine learning to discover statistical inefficiencies in financial markets and exploit them through algorithmic trading.
Author Yves Hilpisch shows practitioners, students, and academics in both finance and data science practical ways to apply machine learning and deep learning algorithms to finance. Thanks to lots of self-contained Python examples, you’ll be able to replicate all results and figures presented in the book.
In five parts, this guide helps you:
- Learn central notions and algorithms from AI, including recent breakthroughs on the way to artificial general intelligence (AGI) and superintelligence (SI)
- Understand why data-driven finance, AI, and machine learning will have a lasting impact on financial theory and practice
- Apply neural networks and reinforcement learning to discover statistical inefficiencies in financial markets
- Identify and exploit economic inefficiencies through backtesting and algorithmic trading–the automated execution of trading strategies
- Understand how AI will influence the competitive dynamics in the financial industry and what the potential emergence of a financial singularity might bring about
Table of Contents
Part I. Machine Intelligence
Chapter 1. Artificial Intelligence
Chapter 2. Superintelligence
Part II. Finance and Machine Learning
Chapter 3. Normative Finance
Chapter 4. Data-Driven Finance
Chapter 5. Machine Learning
Chapter 6. AI-First Finance
Part III. Statistical Inefficiencies
Chapter 7. Dense Neural Networks
Chapter 8. Recurrent Neural Networks
Chapter 9. Reinforcement Learning
Part IV. Algorithmic Trading
Chapter 10. Vectorized Backtesting
Chapter 11. Risk Management
Chapter 12. Execution and Deployment
Part V. Outlook
Chapter 13. AI-Based Competition
Chapter 14. Financial Singularity
Part VI. Appendices
Appendix A. Interactive Neural Networks
Appendix B. Neural Network Classes
Appendix C. Convolutional Neural Networks
From the Preface
The application of AI to financial trading is still a nascent field, although at the time of writing there are a number of other books available that cover this topic to some extent. Many of these publications, however, fail to show what it means to economically exploit statistical inefficiencies.
Some hedge funds already claim to exclusively rely on machine learning to manage their investors’ capital. A prominent example is The Voleon Group, a hedge fund that reported more than six billion dollars (USD) in assets under management at the end of 2019 (see Lee and Karsh 2020). The difficulty of relying on machine learning to outsmart the financial markets is reflected in the fund’s performance of 7% for 2019, a year during which the S&P 500 stock index rose by almost 30%.
This book is based on years of practical experience in developing, backtesting, and deploying AI-powered algorithmic trading strategies. The approaches and examples presented are mostly based on my own research since the field is, by nature, not only nascent, but also rather secretive.
The exposition and the style throughout this book are relentlessly practical, and in many instances the concrete examples are lacking proper theoretical support and/or comprehensive empirical evidence. This book even presents some applications and examples that might be vehemently criticized by experts in finance and/or machine learning.
For example, some experts in machine and deep learning, such as François Chollet (2017), outright doubt that prediction in financial markets is possible. Certain experts in finance, such as Robert Shiller (2015), doubt that there will ever be something like a financial singularity. Others active at the intersection of the two domains, such as Marcos López de Prado (2018), argue that the use of machine learning for financial trading and investing requires an industrial-scale effort with large teams and huge budgets.
This book does not try to provide a balanced view of or a comprehensive set of references for all the topics covered. The presentation is driven by the personal opinions and experiences of the author, as well as by practical considerations when providing concrete examples and Python code. Many of the examples are also chosen and tweaked to drive home certain points or to show encouraging results. Therefore, it can certainly be argued that results from many examples presented in the book suffer from data snooping and overfitting (for a discussion of these topics, see Hilpisch 2020, ch. 4).
The major goal of this book is to empower the reader to use the code examples in the book as a framework to explore the exciting space of AI applied to financial trading. To achieve this goal, the book relies throughout on a number of simplifying assumptions and primarily on financial time series data and features derived directly from such data. In practical applications, a restriction to financial time series data is of course not necessary—a great variety of other types of data and data sources could be used as well. This book’s approach to deriving features implicitly assumes that financial time series and features derived from them show patterns that, at least to some extent, persist over time and that can be used to predict the direction of future movements.
Against this background, all examples and code presented in this book are technical and illustrative in nature and do not represent any recommendation or investment advice.
For those who want to deploy approaches and algorithmic trading strategies presented in this book, my book Python for Algorithmic Trading: From Idea to Cloud Deployment (O’Reilly) provides more process-oriented and technical details. The two books complement each other in many respects. For readers who are just getting started with Python for finance or who are seeking a refresher and reference manual, my book Python for Finance: Mastering Data-Driven Finance (O’Reilly) covers a comprehensive set of important topics and fundamental skills in Python as applied to the financial domain.
About the Author
Dr. Yves J. Hilpisch is founder and managing partner of The Python Quants (http://tpq.io), a group that focuses on the use of open source technologies for financial data science, algorithmic trading and computational finance. He is the author of the books Python for Finance (O’Reilly, 2014), Derivatives Analytics with Python (Wiley, 2015) and Listed Volatility and Variance Derivatives (Wiley, 2017). Yves lectures on computational finance at the CQF Program (http://cqf.com), on data science at htw saar University of Applied Sciences (http://htwsaar.de), and is the director for the online training program leading to the first Python for Finance University Certificate (awarded by htw saar).


نقد و بررسیها
هنوز بررسیای ثبت نشده است.