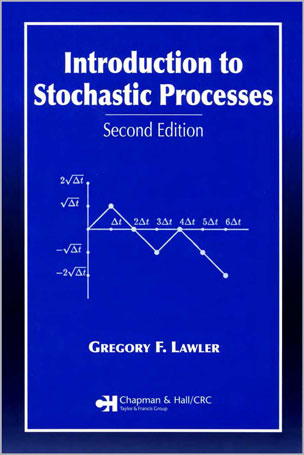
Second Edition provides quick access to important foundations of probability theory applicable to problems in many fields. Assuming that you have a reasonable level of computer literacy, the ability to write simple programs, and the access to software for linear algebra computations, the author approaches the problems and theorems with a focus on stochastic processes evolving with time, rather than a particular emphasis on measure theory.
For those lacking in exposure to linear differential and difference equations, the author begins with a brief introduction to these concepts. He proceeds to discuss Markov chains, optimal stopping, martingales, and Brownian motion. The book concludes with a chapter on stochastic integration. The author supplies many basic, general examples and provides exercises at the end of each chapter.
New to the Second Edition:
- Expanded chapter on stochastic integration that introduces modern mathematical finance
- Introduction of Girsanov transformation and the Feynman-Kac formula
- Expanded discussion of Itô’s formula and the Black-Scholes formula for pricing options
- New topics such as Doob’s maximal inequality and a discussion on self similarity in the chapter on Brownian motion
- Applicable to the fields of mathematics, statistics, and engineering as well as computer science, economics, business, biological science, psychology, and engineering, this concise introduction is an excellent resource both for students and professionals.
Table of Contents
Chapter 0 Preliminaries
Chapter 1 Finite Markov Chains
Chapter 2 Countable Markov Chains
Chapter 3 Continuous-Time Markov Chains
Chapter 4 Optimal Stopping
Chapter 5 Martingales
Chapter 6 Renewal Processes
Chapter 7 Reversible Markov Chains
Chapter 8 Brownian Motion
Chapter 9 Stochastic Integration
About the Author
Gregory F. Lawler is a prominent mathematician known for his contributions to probability theory, particularly in areas such as stochastic processes and Markov chains. He has also made significant contributions to mathematical physics, especially in the field of statistical mechanics.


نقد و بررسیها
هنوز بررسیای ثبت نشده است.