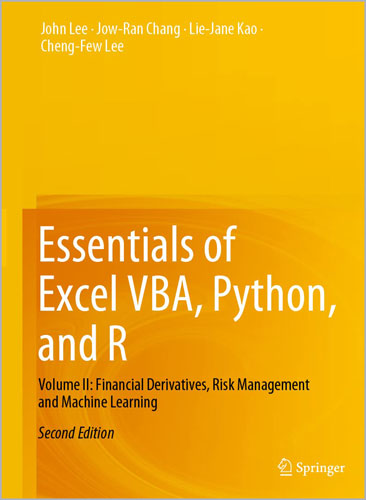
This advanced textbook for business statistics teaches, statistical analyses and research methods utilizing business case studies and financial data with the applications of Excel VBA, Python and R. Each chapter engages the reader with sample data drawn from individual stocks, stock indices, options, and futures. Now in its second edition, it has been expanded into two volumes, each of which is devoted to specific parts of the business analytics curriculum. To reflect the current age of data science and machine learning, the used applications have been updated from Minitab and SAS to Python and R, so that readers will be better prepared for the current industry.
This second volume is designed for advanced courses in financial derivatives, risk management, and machine learning and financial management. In this volume we extensively use Excel, Python, and R to analyze the above-mentioned topics. It is also a comprehensive reference for active statistical finance scholars and business analysts who are looking to upgrade their toolkits. Readers can look to the first volume for dedicated content on financial statistics, and portfolio analysis.
Table of Contents
1 Introduction
PART 1 Excel VBA
2 Introduction to Excel Programming and Excel 365 Only Features
3 Introduction to VBA Programming
4 Professional Techniques Used in Excel and VBA
PART 2 Financial Derivatives
5 Binomial Option Pricing Model Decision Tree Approach
6 Microsoft Excel Approach to Estimating Alternative Option Pricing Models
7 Alternative Methods to Estimate Implied Variance
8 Greek Letters and Portfolio Insurance
9 Portfolio Analysis and Option Strategies
10 Simulation and Its Application
PART 3 Applications of Python, Machine Learning for Financial Derivatives and Risk Management
11 Linear Models for Regression
12 Kernel Linear Model
13 Neural Networks and Deep Learning Algorithm
14 Alternative Machine Learning Methods for Credit Card Default Forecasting*
15 Deep Learning and Its Application to Credit Card Delinquency Forecasting
16 Binomial/Trinomial Tree Option Pricing Using Python
PART 4 Financial Management
17 Financial Ratio Analysis and Its Applications
18 Time Value of Money Determinations and Their Applications
19 Capital Budgeting Method Under Certainty and Uncertainty
20 Financial Analysis, Planning, and Forecasting
PART 5 Applications of R Programs for Financial Analysis and Derivatives
21 Hedge Ratio Estimation Methods and Their Applications
22 Application of Simultaneous Equation in Finance Research: Methods and Empirical Results
23 Three Alternative Programs to Estimate Binomial Option Pricing Model and Black and Scholes Option Pricing Model
About the Authors
Cheng-Few Lee is a Distinguished Professor of Finance at Rutgers Business School, Rutgers University and was chairperson of the Department of Finance from 1988–1995. He has also served on the faculty of the University of Illinois (IBE Professor of Finance) and the University of Georgia. He has maintained academic and consulting ties in Taiwan, Hong Kong, China and the United States for the past three decades. He has been a consultant to many prominent groups including, the American Insurance Group, the World Bank, the United Nations, The Marmon Group Inc., Wintek Corporation, and Polaris Financial Group. Professor Lee founded the Review of Quantitative Finance and Accounting (RQFA) in 1990 and the Review of Pacific Basin Financial Markets and Policies (RPBFMP) in 1998, and serves as managing editor for both journals. He was also a co-editor of the Financial Review (1985-1991) and the Quarterly Review of Economics and Finance (1987-1989).In thepast 42 years, Dr. Lee has written numerous textbooks ranging in subject matters from financial management to corporate finance, security analysis and portfolio management to financial analysis, planning and forecasting, and business statistics. In addition, he edited five popular books, Encyclopedia of Finance (with Alice C. Lee), Handbook of Quantitative Finance and Risk Management (with Alice C. Lee and John Lee), Handbook of Financial Econometrics and Statistics, Handbook of Financial Econometrics, Mathematics, Statistics, and Machine Learning, and Handbook of Investment Analysis, Portfolio Management, and Financial Derivatives. Dr. Lee has also published more than 250 articles in more than 20 different journals in finance, accounting, economics, statistics, and management. Professor Lee was ranked the most published finance professor worldwide during the period 1953-2008.Professor Lee was the intellectual force behind the creation of the new Masters of Quantitative Finance program at Rutgers University. This program began in 2001 and has been ranked as one of the top fifteen quantitative finance programs in the United States. Professor Lee started the Conference on Financial Economics and Accounting in 1989. This conference is a consortium of Rutgers University, New York University, Temple University, University of Maryland, Georgia State University, Tulane University, Indiana University, and University of Toronto. This conference is the most well-known conference in finance and accounting.
John C. Lee is Director of the Center for PBBEF Research. A Microsoft Certified Professional in Microsoft Visual Basic and Microsoft Excel VBA, Mr. Lee has worked over 20 years in both the business and technical fields as an accountant, auditor, systems analyst, as well as a business software developer. Formerly, the Senior Technology Officer at the Chase Manhattan Bank and Assistant Vice Presidentat Merrill Lynch, he is also the author of Business and Financial Statistics Using Minitab 12 and Microsoft Excel 97, as well as Financial Analysis, Planning and Forecasting with Cheng-Few Lee and Alice Lee.


نقد و بررسیها
هنوز بررسیای ثبت نشده است.